Local Payment Infrastructure as a Gateway to Global Commerce
Why connecting local payment rails is becoming essential for businesses that want to scale across African and international markets
Introduction: Global Commerce Still Depends on Local Infrastructure
Digital commerce is increasingly global.
A business can launch a website in one country, acquire customers in another, work with suppliers across several regions, and manage operations through cloud-based platforms.
Payments, however, remain deeply local.
Customers do not necessarily want to pay using the methods preferred by an international merchant. They use the financial infrastructure available and trusted in their own market: bank transfers, mobile money, cards, wallets, instant payment systems, POS networks, and other domestic payment methods.
This creates one of the central challenges of international commerce.
Businesses want global reach, but successful payment acceptance often requires local connectivity.
Across Africa, where payment ecosystems vary significantly between countries, this distinction is particularly important. A payment strategy that works in one market may perform very differently in another.
Local payment infrastructure therefore should not be viewed as an obstacle to globalization.
Increasingly, it is the gateway that makes global commerce possible.
Global Businesses Meet Local Payment Behavior
International expansion is often approached from the perspective of products, customers, logistics, and marketing.
Payments can appear deceptively simple.
A business connects a global payment provider and assumes customers will be able to pay.
But payment availability does not necessarily mean payment accessibility.
Consumers may prefer local methods because they are:
- familiar
- widely available
- connected to existing accounts or wallets
- priced appropriately
- trusted
- optimized for local financial behavior
This means the checkout experience needs to reflect how people actually transact.
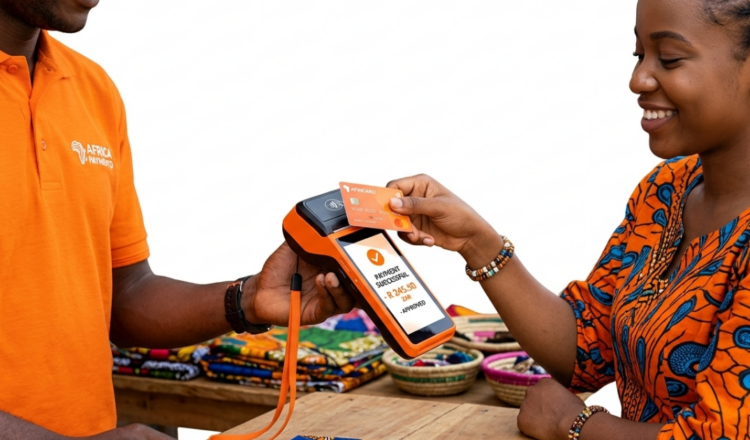
A global business entering African markets may therefore need to support a combination of cards, mobile money, bank transfers, wallets, and other domestic rails.
The closer payment infrastructure is to local behavior, the easier it becomes to turn international demand into completed transactions.
Africa Is Not One Payment Market
One of the biggest mistakes businesses can make is treating Africa as a single payment ecosystem.
Payment behavior differs substantially across the continent.
Mobile money plays a central role in some markets. Bank transfers and instant payment systems are particularly important in others. Cards have stronger penetration in certain customer segments, while cash and agent-assisted transactions remain relevant elsewhere.
Regulation, currencies, banking infrastructure, settlement systems, and provider availability also differ.
For businesses expanding across several African countries, this creates a technical challenge.
Every new market can introduce:
- new payment providers
- new APIs
- different settlement processes
- additional compliance requirements
- new currencies
- different reconciliation formats
Global expansion therefore creates local infrastructure complexity.
Localization Is More Than Currency
Payment localization is sometimes reduced to displaying prices in the customer’s currency.
That is only one part of the experience.
True payment localization involves understanding the entire transaction environment.
A localized payment experience may include:
- local currency
- preferred payment methods
- domestic banking rails
- familiar authentication flows
- locally relevant checkout options
- appropriate settlement infrastructure
A customer should not need to understand the merchant’s international payment architecture.
The infrastructure should translate global commerce into a payment experience that feels local.
Local Payment Rails Can Improve Accessibility
Supporting local payment infrastructure can expand the number of customers a business is capable of serving.
A merchant relying only on international card networks may unintentionally exclude customers who primarily transact through other channels.
Connecting additional rails creates more ways to complete a transaction.
This matters not only for consumers.
African businesses themselves may rely on different financial systems when paying:
- suppliers
- contractors
- employees
- marketplaces
- logistics providers
- international partners
Global commerce therefore requires both local acceptance and local payout capabilities.
The Real Challenge Is Integration
The problem is rarely that local payment methods do not exist.
The problem is connecting them efficiently.
A business could theoretically integrate every provider independently.
But that model becomes difficult to scale.
Imagine a company entering five markets and connecting four payment providers in each.
It could quickly be managing twenty separate integrations.
Each integration may have different:
- API specifications
- authentication methods
- transaction statuses
- reporting formats
- settlement cycles
- error codes
Expansion increases complexity exponentially.
This is why payment infrastructure becomes strategically important.
Payment Orchestration Creates a Common Layer
Payment orchestration can reduce this complexity by creating a unified layer between businesses and multiple payment providers.
Instead of rebuilding the merchant’s payment architecture for every new provider, businesses connect through a common infrastructure layer.
The orchestration platform manages connectivity underneath.
This allows companies to add:
- local payment providers
- international processors
- alternative payment methods
- bank rails
- mobile money
without redesigning their entire payment stack.
For businesses expanding across Africa, this architecture can make localization significantly more scalable.
Local Infrastructure Can Support Global Checkout
A global checkout does not necessarily need a single global payment rail.
In fact, the opposite model may prove more effective.
The customer interacts with a payment method they already know.
Behind the scenes, infrastructure connects that local transaction to the merchant’s broader international financial operations.
The architecture might look like:
Customer → Local Payment Method → Local Infrastructure → Orchestration Layer → Merchant
The customer sees familiarity.
The merchant gets connectivity.
Infrastructure connects the two.
This is how local payment systems become part of global commerce rather than alternatives to it.
Routing Makes Multiple Providers More Powerful
Once businesses connect multiple payment providers, another opportunity appears: intelligent routing.
Not every provider performs equally under every condition.
Performance can vary according to:
- country
- payment method
- transaction type
- currency
- provider availability
- transaction value
Payment orchestration can apply routing logic to determine which provider should process a transaction.
If one route becomes unavailable, eligible payments can potentially move to another.
As AI becomes integrated into payment infrastructure, this routing can become increasingly dynamic, using real-time performance information to optimize decisions.
Local connectivity therefore creates optionality.
Orchestration turns that optionality into operational resilience.
Local Infrastructure Matters for Payouts Too
International commerce is not only about collecting money.
Businesses also need to distribute it.
Marketplaces need to pay sellers.
Platforms need to compensate service providers.
Companies need to pay contractors.
International businesses need to settle with local partners.
This makes payout infrastructure just as important as payment acceptance.
A company may accept payments globally but still struggle if it cannot efficiently distribute funds into local financial ecosystems.
Connecting local banking, wallet, and other payout rails creates a more complete commercial infrastructure.
The future of international payments therefore depends increasingly on two-way connectivity:
global-to-local and local-to-global.
Settlement Is Where Infrastructure Becomes Critical
The customer experience may end when a payment is approved.
The financial process does not.
Funds still need to move through settlement systems and ultimately reach the merchant or another intended recipient.
Across multiple markets, this can involve:
- different settlement schedules
- currencies
- banking partners
- liquidity requirements
- reconciliation processes
Businesses need infrastructure capable of managing these operational layers.
Otherwise, international growth can produce increasingly complex back-office operations.
The strongest payment infrastructure therefore connects checkout with settlement, reporting, and reconciliation.
Reconciliation Must Scale With Commerce
A business processing transactions through several providers needs to understand exactly what happened to every payment.
Finance teams need to connect:
- orders
- transactions
- refunds
- fees
- payouts
- settlements
If every local provider uses a different reporting structure, reconciliation becomes difficult.
Unified payment infrastructure can normalize this information.
Instead of forcing finance teams to interpret multiple provider formats manually, businesses can create a more consistent operational view across markets.
This is an important but often underestimated component of international scalability.
Local Infrastructure Can Strengthen Payment Resilience
Depending on one provider creates concentration risk.
If that provider experiences downtime, technical problems, or local connectivity issues, payments may fail.
Multi-provider infrastructure creates redundancy.
Businesses can potentially maintain several routes for important markets.
If one connection becomes unavailable, traffic can move through another eligible route.
For merchants, this can mean:
- fewer disruptions
- better transaction continuity
- more resilient operations
Local payment infrastructure therefore contributes not only to localization but also to reliability.
APIs Turn Local Rails Into Global Building Blocks
APIs are central to making this model scalable.
Local financial services historically operated through separate technical environments.
API-first infrastructure allows these services to become modular components of larger payment ecosystems.
Through APIs, businesses can connect capabilities such as:
- payment initiation
- transaction verification
- refunds
- payout processing
- balance information
- settlement reporting
A local payment provider no longer needs to remain an isolated endpoint.
It can become one component inside a larger international payment architecture.
Open Banking Could Expand Local Connectivity
Open banking may accelerate this transition further.
As banks expose more financial capabilities through secure APIs, payment platforms can potentially integrate domestic bank payments more efficiently.
This can expand account-to-account payment capabilities and provide businesses with additional alternatives to traditional payment methods.
Open banking can also improve access to transaction and account information where regulation and customer consent permit it.
Combined with payment orchestration, these capabilities can make domestic banking infrastructure easier to integrate into international commerce.
AI Can Optimize Local-to-Global Connectivity
The next step is intelligence.
Once infrastructure connects multiple providers and payment rails, AI can help determine how those connections should be used.
An intelligent payment system could analyze:
- transaction success rates
- processing costs
- network availability
- settlement speed
- fraud risk
- historical provider performance
It could then optimize routing dynamically.
This creates a powerful combination:
local connectivity provides reach; orchestration provides control; AI provides optimization.
The underlying infrastructure remains essential because AI can only optimize the payment options that are actually connected.
International Commerce Requires Regulatory Infrastructure Too
Technology alone cannot create international payment connectivity.
Payments remain regulated financial activity.
Businesses expanding across African markets need to consider requirements related to:
- licensing
- KYC and KYB
- AML controls
- consumer protection
- data governance
- transaction monitoring
- reporting
- foreign exchange
This means scalable payment infrastructure needs configurable compliance capabilities.
The objective is not to eliminate local regulatory differences.
It is to build architecture capable of accommodating them without creating an entirely separate technology stack for every jurisdiction.
Local Infrastructure Supports African Businesses Going Global
The local-to-global relationship works in both directions.
African merchants increasingly participate in international digital commerce.
Technology companies sell services abroad. E-commerce businesses reach international customers. Platforms work with global partners. SMEs increasingly interact with cross-border supply chains.
These businesses need infrastructure capable of connecting domestic financial operations with international payment flows.
Without that connectivity, global commerce remains operationally difficult even when international demand exists.
Strong local payment infrastructure can therefore become an export enabler.
It helps African businesses participate more effectively in the global digital economy.
The Future Is Not One Global Payment Method
The payment industry has long pursued standardization.
But global commerce does not necessarily require everyone to use the same payment method.
A more realistic future may be based on interoperability.
Consumers continue using local financial systems.
Merchants continue operating across global markets.
Infrastructure translates between them.
Instead of replacing local rails with one global network, payment platforms can connect multiple local systems through common APIs, orchestration, and settlement infrastructure.
This preserves local relevance while enabling international scale.
How Unipesa Connects Local Infrastructure With Broader Commerce
Unipesa, a portfolio company of Velex Investments, is focused on building scalable fintech infrastructure for businesses operating across African markets.
Its technology supports payment orchestration, API-first integrations, POS infrastructure, digital wallets, lending solutions, communication services, and international payment capabilities.
This infrastructure-first model addresses one of the fundamental requirements of international expansion: connecting businesses to financial services that reflect how individual markets actually operate.
Rather than forcing merchants to manage fragmented payment connections independently, unified infrastructure can create a common layer across providers and services.
That allows businesses to maintain local payment relevance while building toward regional and international scale.
The result is a different way of thinking about global payments:
global reach does not require eliminating local infrastructure. It requires connecting it.
Conclusion
Global commerce may happen online, but payments remain rooted in local financial ecosystems.
Customers use familiar payment methods. Merchants depend on domestic providers. Banks operate within national systems. Regulation remains jurisdiction-specific.
Trying to bypass this complexity is unlikely to create truly global payment experiences.
Connecting it can.
Local payment infrastructure bridges international businesses and the financial behavior of the markets they want to serve.
Payment orchestration makes those connections manageable. APIs make them scalable. AI can make them more intelligent. Interoperability allows them to become part of a broader financial network.
For businesses expanding across Africa—and African businesses expanding internationally—the implication is clear:
The gateway to global commerce increasingly begins with infrastructure that works locally.