How Smart POS Terminals Are Transforming Payment Acceptance in Africa
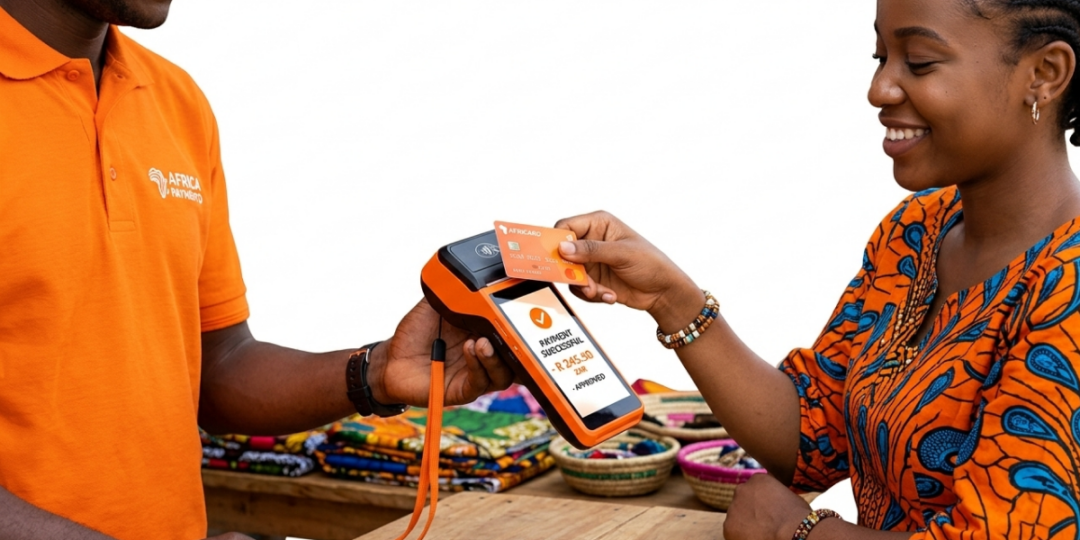
Why the evolution from traditional card readers to intelligent, connected POS platforms is creating new opportunities for African merchants, payment service providers, and fintech infrastructure companies.
Introduction: The Future of Payment Acceptance Is More Than a Terminal
Across Africa, the way businesses accept payments is undergoing a fundamental transformation. Traditional point-of-sale terminals, once designed primarily to process card transactions, are evolving into connected financial platforms capable of supporting multiple payment methods, merchant services, business analytics, and embedded financial products.
For decades, payment acceptance depended heavily on dedicated hardware and relatively limited transaction functionality. Merchants used terminals to process card payments, while other financial activities, including mobile money transfers, bank payments, inventory management, and business reporting, often required separate systems.
That fragmented approach is becoming increasingly difficult to maintain.
African consumers use a diverse combination of payment methods, including mobile money, cards, bank transfers, digital wallets, and QR payments. Merchants need technology capable of supporting these preferences without creating additional operational complexity.
Smart POS terminals are emerging as an important part of that solution.
Unlike traditional payment terminals, modern smart POS devices combine payment acceptance with software-driven functionality, cloud connectivity, and integration capabilities. They can serve as a central interface for transactions while connecting merchants to a broader ecosystem of financial and business services.
For payment service providers (PSPs), this evolution represents more than an opportunity to distribute new hardware. It creates the foundation for scalable merchant platforms, stronger customer relationships, and additional revenue streams.
The future of POS infrastructure in Africa will therefore be defined not simply by how many terminals are deployed, but by how effectively those terminals connect merchants to the digital financial economy.
From Traditional Card Readers to Smart POS Platforms
Traditional POS terminals were developed around a relatively narrow function: accepting electronic card payments.
A merchant entered the transaction amount, the customer presented a card, and the terminal communicated with the acquiring infrastructure to process the payment. The device then displayed the transaction result and, in many cases, printed a receipt.
This model remains important, particularly in markets where card payments represent a substantial share of merchant transactions.
However, traditional terminals were not originally designed to operate as comprehensive business platforms. Their functionality was often limited, software updates could be difficult, and integration with external applications was restricted.
Smart POS terminals introduce a different architecture.
Modern devices commonly use operating systems capable of supporting multiple applications, wireless connectivity, touchscreen interfaces, and centralized device management.
Instead of performing only payment authorization, a smart POS terminal can potentially support transaction reporting, merchant applications, digital receipts, loyalty programs, inventory management, and additional financial services.
The terminal becomes a programmable endpoint connected to a broader technology platform.
This distinction is fundamental because the value of the POS increasingly comes from the software and financial infrastructure operating behind the device.
Why African Merchants Need More Flexible Payment Acceptance
Africa’s payment landscape is characterized by diversity rather than a single dominant payment method across the continent.
Mobile money plays a central role in several East African markets, while cards, bank transfers, instant payments, and other digital methods have varying levels of adoption across different countries.
A merchant serving local customers may therefore need to accept several forms of payment.
For example, one customer may prefer a bank card, another may use mobile money, and a third may choose a QR-based payment or bank transfer.
If each payment method requires a separate device or operational process, the merchant faces unnecessary complexity.
Different payment channels may produce separate transaction reports, settlement schedules, and reconciliation requirements. Employees may also need training across multiple systems.
Smart POS infrastructure can help consolidate these interactions through a common merchant interface.
Rather than forcing businesses to organize their operations around individual payment providers, the platform can be designed around the merchant’s needs.
The objective is straightforward: allow merchants to accept the payment methods their customers prefer while simplifying the technology required to manage them.
Multi-Payment Acceptance Is Becoming a Core POS Requirement
One of the most important advantages of smart POS infrastructure is its potential to support multiple payment methods.
Depending on the device, software, provider integrations, and local regulatory arrangements, a smart POS platform may support cards, contactless payments, QR transactions, mobile money, digital wallets, and bank-based payment methods.
This flexibility is particularly valuable in African markets because payment preferences differ significantly between customer segments and geographic locations.
A retailer operating in an urban shopping center may encounter different payment behavior from a merchant serving customers in a smaller town.
Similarly, a business operating across several countries may need different local payment connections.
A multi-payment POS architecture can reduce the need to deploy entirely separate merchant systems for every market.
The terminal acts as the customer-facing interface, while the underlying payment infrastructure manages connectivity with supported providers.
This creates a more adaptable model for both merchants and PSPs.
Payment Orchestration Makes Smart POS More Powerful
The ability to accept multiple payment methods is only part of the transformation.
Payment orchestration can make smart POS platforms significantly more flexible by providing a common infrastructure layer across different payment providers.
In a traditional environment, each provider connection may require separate transaction logic, reporting, and operational processes.
Payment orchestration allows businesses to coordinate multiple connections through a more unified architecture.
A simplified transaction flow becomes:
Customer → Smart POS Terminal → Payment Orchestration → Payment Provider → Financial Network
The smart POS terminal initiates the payment experience, while the orchestration layer determines how the transaction interacts with the available infrastructure.
Depending on the platform, routing decisions may consider payment method, transaction characteristics, provider availability, and business rules.
If a provider experiences technical difficulties, eligible transactions may be processed through another available route where the payment method and integration arrangements permit.
This can improve operational resilience and reduce dependence on individual providers.
For PSPs operating across African markets, orchestration can also simplify the management of diverse local payment connections.
The strategic advantage lies in separating the merchant experience from the complexity of the underlying payment ecosystem.
Cloud Connectivity Changes POS Management
Smart POS terminals are increasingly managed through cloud-based infrastructure.
This allows PSPs and merchant service providers to monitor devices, distribute software updates, configure applications, and manage certain operational functions remotely.
Traditional terminal management often required more direct intervention, particularly when software functionality changed.
Cloud-connected platforms can make large device networks easier to operate.
A PSP managing thousands of terminals may need visibility into device activity, software versions, transaction performance, and operational issues.
Centralized management can help identify inactive devices, detect technical problems, and support more consistent configuration across the network.
For merchants, cloud connectivity can also improve access to transaction information.
Instead of relying exclusively on reports generated by the terminal itself, businesses may be able to view payment activity through connected dashboards or applications.
This makes POS infrastructure part of a broader digital operating environment.
Smart POS Is Becoming a Merchant Management Platform
Payment acceptance is only one component of running a business.
Merchants also need to manage products, employees, customers, inventory, and financial records.
Modern smart POS platforms can integrate some of these capabilities into the same environment used for transactions.
For example, a retailer may use a connected POS application to record sales, monitor inventory, generate reports, and manage refunds.
A restaurant may connect payment acceptance with order management and employee workflows.
A service business may use POS software to track customer payments and produce digital receipts.
These functions reduce the need for merchants to operate completely separate systems.
They also create opportunities for PSPs to provide additional value beyond basic payment processing.
A merchant that relies on a POS platform for several business functions may develop a deeper relationship with the provider than one using a terminal solely for card acceptance.
This changes the commercial role of POS infrastructure from a transaction tool to a merchant operating platform.
Smart POS Can Improve Merchant Visibility and Reporting
Financial visibility is a persistent challenge for many small and medium-sized businesses.
Merchants may receive payments through several channels but lack a consolidated view of their financial activity.
Smart POS platforms can help address this problem by connecting transaction information with reporting tools.
Depending on the infrastructure, merchants may be able to monitor daily sales, payment methods, transaction volumes, refunds, and settlement activity.
This information can support better operational decisions.
A merchant can identify busy trading periods, compare sales performance, and understand which payment methods customers use most frequently.
For PSPs, transaction reporting can also reduce support requirements by making payment information more accessible.
However, effective reporting depends on the quality and completeness of the underlying data.
A smart terminal alone cannot create a unified financial picture if the payment infrastructure behind it remains disconnected.
This is why APIs, payment orchestration, and centralized transaction management are essential to the broader POS platform model.
POS Data Creates Opportunities for Embedded Finance
One of the most significant long-term opportunities associated with smart POS infrastructure is embedded finance.
As merchants process transactions through connected platforms, they generate information about business activity.
This may include transaction frequency, average sales value, revenue patterns, refunds, and seasonal changes.
With appropriate consent, data governance, and regulatory controls, this information can potentially support additional financial products.
Merchant lending is a particularly relevant example.
Traditional lenders may have limited visibility into the daily operations of smaller businesses. Transaction data can provide supplementary information about commercial activity and cash-flow patterns.
A lender could potentially use these signals alongside other information when evaluating a merchant’s financing application.
The POS platform then becomes a distribution channel for working-capital products.
The merchant continues using the same technology environment, while additional financial services are delivered through connected infrastructure.
This creates opportunities for PSPs to develop broader merchant relationships without necessarily becoming lenders themselves.
Smart POS and Merchant Lending
Merchant lending illustrates how payment infrastructure and financial products can converge.
A business using a smart POS platform may generate a consistent record of digital transactions.
That information can potentially help a licensed lending partner assess the merchant’s financial activity.
If financing is approved, funds may be disbursed through an appropriate bank account, wallet, or other supported channel.
Repayments can also be connected to digital payment infrastructure.
Depending on the product and applicable regulations, repayment structures may be designed around fixed schedules or eligible transaction flows.
The resulting architecture connects several financial capabilities:
POS Transactions → Merchant Data → Credit Assessment → Financing → Repayment
The POS does not independently make lending decisions.
Instead, it provides a connection between merchant activity and the infrastructure supporting financial products.
For African SMEs, this integration could make certain forms of financing more accessible and operationally convenient.
Digital Wallets Expand POS Functionality
Smart POS platforms can also connect with digital wallet infrastructure.
Wallets may allow merchants or customers to receive funds, manage balances, make transfers, or access other supported financial services.
When wallet functionality is integrated into the broader POS environment, merchants may gain additional options for managing payment activity.
For example, a platform could connect payment acceptance with a merchant wallet used for eligible transfers or business expenses.
The exact capabilities depend on the regulatory model, financial partners, and infrastructure configuration.
The important development is architectural.
Instead of treating payment acceptance and wallet services as completely separate products, connected infrastructure can bring them into a common merchant experience.
This is another step toward POS becoming a broader financial platform.
QR Payments Are Expanding POS Capabilities
QR payments are becoming increasingly relevant as financial providers seek more flexible and accessible payment experiences.
A smart POS terminal may display a QR code that allows a customer to initiate payment through a supported wallet or banking application.
Alternatively, a terminal equipped with suitable scanning capabilities may read a customer-presented code.
These models can reduce dependence on physical cards and expand the range of payment methods available to merchants.
QR-based acceptance is particularly useful when supported by interoperable payment infrastructure.
If a QR standard works across multiple participating providers, merchants may be able to accept payments from customers using different financial applications.
However, interoperability depends on the relevant payment scheme, technical standards, and participating institutions.
A QR code by itself does not guarantee that every wallet or banking application can use it.
For PSPs, the opportunity is to connect QR acceptance with broader payment infrastructure rather than treating it as another isolated payment method.
SoftPOS Is Changing the Hardware Economics
The evolution of smart POS is also connected to the rise of Software Point of Sale, commonly known as SoftPOS.
SoftPOS allows compatible smartphones or tablets to accept certain contactless payments using appropriate software and certified technology.
This can reduce the need for dedicated payment hardware in some merchant environments.
For smaller businesses, lower hardware requirements may make digital payment acceptance more accessible.
For PSPs, software-based acceptance can create new distribution models.
Instead of deploying specialized terminals to every merchant, providers may be able to activate compatible devices through software.
However, SoftPOS does not replace every use case for dedicated terminals.
Businesses with high transaction volumes, specialized operational requirements, or integrated peripherals may continue to benefit from purpose-built POS hardware.
The broader trend is that payment acceptance is becoming increasingly software-defined.
The value shifts toward the infrastructure connecting devices, merchants, and payment providers.
Smart POS Can Strengthen Agent Banking Networks
POS infrastructure also plays an important role in agent banking across African markets.
Agents provide physical access points for customers who need financial services outside traditional bank branches.
Depending on local regulations and provider arrangements, agent networks may support cash-in and cash-out, transfers, bill payments, account services, and other financial transactions.
Smart POS technology can expand the range of capabilities available through these networks.
A connected device may provide a common interface for several services while allowing operators to monitor activity across the network.
This creates opportunities to improve agent productivity and operational visibility.
Instead of measuring success only by the number of terminals deployed, providers can evaluate active usage, transaction volumes, service availability, and the financial products delivered through each location.
The next generation of agent banking will increasingly depend on the quality of the infrastructure connecting physical agents to digital financial services.
Better Device Management Can Improve Network Economics
For PSPs operating large POS networks, hardware distribution is only one component of the business.
Devices need to be activated, maintained, monitored, and supported.
Inactive terminals create costs without generating transaction revenue.
Technical failures can interrupt merchant operations and increase support expenses.
Smart POS infrastructure can improve network management through centralized monitoring and software controls.
Providers may be able to identify devices with low activity, detect connectivity issues, and prioritize operational support.
This can improve resource allocation.
A PSP may discover that certain locations require additional merchant training, while others would benefit from different payment capabilities.
Data-driven network management can therefore become an important factor in POS profitability.
The economic objective is not simply to deploy more devices.
It is to increase the productivity and reliability of the connected network.
Security Is Becoming More Important as POS Functionality Expands
As smart POS terminals support more applications and financial services, their security requirements become more complex.
Traditional payment terminals were designed around tightly controlled transaction environments.
Modern smart devices may support additional software, connectivity options, and integrations.
This increases the importance of secure device management, application controls, authentication, encryption, and monitoring.
Payment card acceptance may also require compliance with applicable industry security standards and certification requirements.
For PSPs, security must extend beyond individual transactions.
The platform needs to protect merchant access, device identities, financial data, and communication between terminals and backend infrastructure.
Remote software management should also include appropriate controls to prevent unauthorized modifications.
As POS evolves into a financial platform, security becomes a foundational infrastructure requirement rather than simply a feature of the payment terminal.
AI Can Make POS Platforms More Intelligent
Artificial intelligence creates another opportunity for smart POS infrastructure.
Connected terminals generate transaction and operational data that can support more advanced analysis.
AI systems may help identify unusual transaction patterns, forecast merchant activity, detect operational anomalies, and improve payment performance.
For example, a PSP could analyze transaction failures across its terminal network to identify a provider experiencing technical difficulties.
A merchant analytics platform could use historical sales information to identify seasonal patterns or estimate future demand.
AI may also support fraud detection by identifying behavior that differs from established transaction patterns.
These capabilities depend on reliable data collection, appropriate governance, and integration with broader financial systems.
The terminal itself does not need to perform every AI calculation.
Instead, it can act as a connected endpoint within a larger intelligent infrastructure environment.
AI Agents Could Transform POS Operations
The next stage may involve AI agents capable of supporting operational workflows.
An AI agent connected to POS infrastructure could potentially monitor terminal performance, investigate transaction failures, or identify unusual settlement patterns.
For example, if a group of terminals begins experiencing elevated payment failure rates, an agent could analyze transaction information and provider performance to identify possible causes.
It might recommend an operational response or prepare an approved configuration change.
Merchant-facing AI assistants could also help businesses understand transaction reports and financial activity through natural-language questions.
A merchant might ask, “Why were my sales lower yesterday?” or “Which payment method generated the most revenue this week?”
The system could retrieve relevant information and provide an explanation.
These applications illustrate how POS infrastructure can evolve beyond recording transactions toward supporting more intelligent financial operations.
White-Label Smart POS Platforms Create Opportunities for PSPs
The growing complexity of POS technology also makes white-label infrastructure increasingly relevant.
Building a complete smart POS ecosystem independently can require significant investment in device software, merchant management, payment integrations, reporting, security, and operational support.
White-label POS platforms can provide reusable technology components that businesses configure for their own commercial models.
For fintech companies and PSPs, this may reduce the need to develop every underlying system before entering the merchant payment market.
A company could focus on building its merchant network, establishing local partnerships, and developing specialized services while integrating existing POS infrastructure.
The level of customization depends on the provider.
Some solutions may support branded interfaces and merchant applications, while others primarily provide backend APIs and device-management capabilities.
The strategic advantage is the ability to separate merchant-facing differentiation from foundational technology development.
From POS Transaction Fees to Platform Revenue
The commercial model for POS providers is also evolving.
Traditional POS businesses often relied heavily on transaction-processing revenue and terminal-related fees.
Smart POS platforms can potentially support a broader range of monetization opportunities.
These may include software subscriptions, merchant analytics, inventory tools, loyalty services, integrations, and additional financial products delivered through appropriate partners.
A PSP offering only payment acceptance may face significant pricing competition.
A PSP providing an integrated merchant platform can compete on a broader value proposition.
This does not mean every additional service will generate meaningful revenue.
Products must solve genuine merchant problems, and pricing must reflect the value delivered.
Nevertheless, the platform model creates opportunities to diversify revenue beyond basic transaction fees.
It also strengthens the commercial relationship between the PSP and the merchant.
The Future of POS in Africa Is Infrastructure-Led
The next generation of African POS platforms will likely be defined by several interconnected developments.
Payment acceptance will become more flexible as terminals support different payment methods and connect to multiple providers.
Cloud infrastructure will make device networks easier to manage.
APIs will connect POS systems with merchant software and financial services.
Embedded finance will create opportunities around wallets, credit, and business financial management.
AI will improve analytics and operational intelligence.
Meanwhile, SoftPOS and other software-based acceptance models will continue changing the relationship between payment hardware and payment infrastructure.
These developments point toward a broader transformation.
The POS terminal is becoming one interface within a connected financial ecosystem.
The underlying infrastructure increasingly determines how valuable that interface can become.
How Unipesa Fits Into the Evolution of Smart POS
Unipesa, a portfolio company of Velex Investments, focuses on building scalable fintech infrastructure for businesses operating across African markets.
Its technology portfolio includes POS infrastructure, payment orchestration, digital wallets, lending solutions, communication services, API-driven integrations, and international payment capabilities.
These capabilities are relevant to the evolution of smart POS because modern merchant platforms increasingly depend on several interconnected financial services.
POS infrastructure provides the merchant-facing transaction environment, while payment orchestration can support connectivity across different payment providers and methods.
API-driven architecture allows POS capabilities to interact with broader financial systems.
Wallet and lending infrastructure can support additional financial products, while communication services can contribute to merchant and customer engagement.
The strategic opportunity lies in connecting these capabilities through a scalable infrastructure model rather than treating each financial service as a separate technology environment.
For fintech companies, PSPs, and businesses developing merchant payment platforms, this approach can reduce duplicated development and support more flexible product expansion.
Unipesa’s infrastructure positioning reflects a broader industry direction: the value of POS increasingly depends on the financial technology ecosystem behind the device.
Conclusion: Smart POS Is Redefining Payment Acceptance
Smart POS terminals are transforming payment acceptance across Africa by expanding the role of the traditional payment device.
What began as a mechanism for processing card transactions is becoming a connected platform for multiple payment methods, merchant management, financial data, and additional financial services.
For merchants, this evolution can simplify operations and improve access to digital financial tools.
For PSPs, it creates opportunities to build stronger merchant relationships, improve network economics, and develop revenue streams beyond basic payment processing.
For fintech infrastructure providers, it increases demand for APIs, payment orchestration, wallet connectivity, lending capabilities, and scalable transaction systems.
The transformation can be summarized as:
Traditional Card Terminal → Connected POS → Smart POS Platform → Integrated Merchant Financial Ecosystem
The future of POS in Africa will not be determined solely by the capabilities of individual devices.
It will depend on how effectively those devices connect merchants, customers, payment providers, and financial services.
The most valuable POS platform will not simply process transactions. It will help merchants participate more effectively in the digital economy while providing the infrastructure for financial services to grow around them.